
UPSC Prelims 2026 · GS Paper I: Consider the following statements about the Non-Banking Financial Companies (NBFCs) in India :1. NBFCs…
Consider the following statements about the Non-Banking Financial Companies (NBFCs) in India :
- 1. NBFCs cannot accept demand deposits.
- 2. All the NBFCs operating in India have to be registered with the RBI.
- 3. NBFCs form part of the payment and settlement system and can issue cheque drawn on itself.
- 4. Deposit insurance facility of Deposit Insurance and Credit Guarantee Corporation (DICGC) is not available to the depositors of deposit taking NBFCs.
Which of the statements given above is/are correct ?
Answer (a) & explanation
Statements 1 and 4 are correct (a). The RBI lists how an NBFC differs from a bank. Statement 1 is right: NBFCs cannot accept demand deposits. Statement 4 is right: depositors of NBFCs get no DICGC insurance cover. Statement 3 is wrong: NBFCs are not part of the payment and settlement system and cannot issue cheques drawn on themselves. Statement 2 is wrong: not every NBFC registers with the RBI; insurers report to IRDAI, merchant bankers and brokers to SEBI, and chit funds to State governments. So options (b), (c) and (d) fail.
Notice the current rules: since 2021, the RBI regulates NBFCs through a Scale-Based Regulation in four layers: Base, Middle, Upper and Top. DICGC covers bank deposits up to ₹5 lakh.
"All the NBFCs" in statement 2. Many finance companies have another regulator.
Answer as per the official UPSC answer key.
Same theme in UPSC Mains
- MAINS UPSC Mains 2026 · GS Paper IV · Q10Vikas is a government officer with over a decade of service in public administration. He has recently moved as the District Collector (DC) of Nainipura, a…
- MAINS UPSC Mains 2026 · GS Paper III · Q2Examine the view that financial inclusion is an integral part of social and economic inclusion in a country like India. Also throw light on the usefulness…
- MAINS UPSC Mains 2025 · GS Paper II · Q14Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism…
Related questions from other years
Which one of the following correctly represents the three key sub-indices of the Financial Inclusion Index (FI-Index) of the Reserve Bank of India (RBI) ?
Answer (c) & explanation
The sub-indices are Access, Usage and Quality (c). The RBI launched the FI-Index in August 2021. It covers banking, investments, insurance, postal services and pension, and gives one value between 0 and 100. Its three parameters are Access (35%), Usage (45%) and Quality (20%). Options (a), (b) and (d) list areas or ideas that are not its sub-indices; GDP contribution and affordability are not parameters.
Notice the logic: usage has the most weight, because an account that is never used does not mean real inclusion. Quality includes financial literacy and consumer protection. The index is published every July, and it has risen steadily, helped by Jan Dhan (2014) and UPI.
Answer as per the official UPSC answer key.
Which one of the following best describes the key objective of India's 'Open Network for Digital Commerce' (ONDC) initiative ?
Answer (c) & explanation
ONDC aims to break the dominance of large platforms (c). The Open Network for Digital Commerce, a DPIIT initiative (2021-22), is an open set of rules, like UPI for shopping. A buyer on one app can buy from a seller listed on another app. This interoperability lets small sellers reach buyers without joining a giant platform. Option (a) is wrong: it does not give the government control of transactions. Option (b) is wrong: private players can join; they are not replaced. Option (d) is wrong: it does not force UPI payments.
Notice ONDC's design: it is a not-for-profit company and part of India's Digital Public Infrastructure, along with Aadhaar, UPI and DigiLocker. It now covers food, groceries and mobility too.
options (a), (b) and (d) use strong words: "all", "replace", "mandate". A public digital platform usually opens a market; it does not take it over.
Answer as per the official UPSC answer key.
Which one of the following statements about Unified Payments Interface (UPI) and Central Bank Digital Currency (Digital Rupee) is not correct ?
Answer (d) & explanation
Statement (d) is not correct (d). Under UPI, money moves between bank accounts; the deposit is a liability of the bank. The Digital Rupee (e₹) is like a currency note in digital form, a direct liability of the RBI, not of users or banks. Option (a) is correct: UPI is a payment system, while the e-rupee is sovereign currency. Option (b) is correct: an e-rupee transfer moves value from wallet to wallet with no separate settlement. Option (c) is correct: e-rupee wallet transactions do not appear in bank statements.
Notice the legal base: the RBI Act was amended in 2022 to let the RBI issue a CBDC. Pilots began that year in wholesale (e₹-W) and retail (e₹-R) forms.
a "not correct" question. Look for the statement that puts the RBI's liability on someone else.
Answer as per the official UPSC answer key.
Which of the following statements about Real-World Assets (RWA) Tokenization are correct ?
- 1. Tokenization is the process of turning real world assets into digital tokens using blockchain technology.
- 2. Tokenization of real world assets offers 24x7 access, promoting financial inclusion.
- 3. Tokenization of real world assets will allow the access to high growth investment opportunities for individuals in India.
Select the answer using the code given below :
Answer (a) & explanation
All three statements are correct (a). Statement 1 is right: tokenization turns a real asset, like a building, bond or gold, into digital tokens recorded on a blockchain. Statement 2 is right: tokens can be traded 24x7, which widens financial inclusion. Statement 3 is right: small, fractional tokens let ordinary individuals get into high-growth investments that once needed crores. So options (b), (c) and (d) fail.
Notice the risks: unclear regulation, cyber threats and weak investor protection. In India, related steps include Fractional Ownership Platforms and REITs and InvITs, which already let small investors own slices of real estate and infrastructure. The RBI is also testing tokenized deposits and government securities in sandbox pilots.
Answer as per the official UPSC answer key.
In the news since
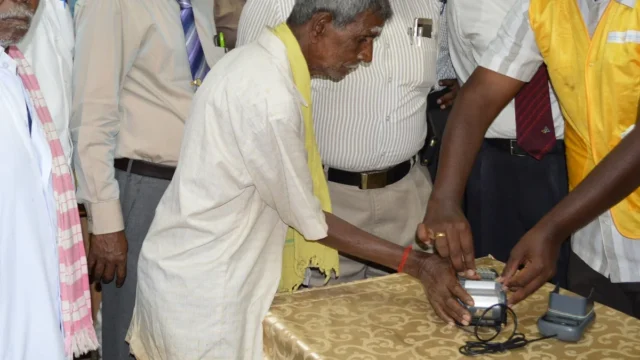
Financial inclusion saturation campaign in 2.70 lakh panchayats and ULBs from 21 October
The Department of Financial Services will run a nationwide campaign from 21 October to 31 December 2026 to saturate financial inclusion schemes in 2.70 lakh gram panchayats and urban local bodies. Bank camps will enrol people in PMJJBY, PMSBY and APY, open Jan Dhan accounts, finish re-KYC and nominations, and spread awareness on digital frauds and unclaimed deposits.
20 Oct 2026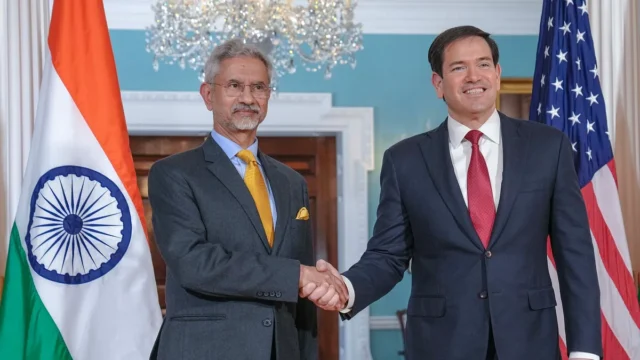
Rubio in Mumbai: India–US trade deal ‘very, very close’; energy and defence on the table
US Secretary of State Marco Rubio began his second India visit of the year in Mumbai on 20 October 2026 and met External Affairs Minister S. Jaishankar on trade, energy, technology and defence. Rubio said the two sides are ‘very, very close’ to a trade deal with ‘a small number of items left’, and praised India’s progress in diversifying energy supplies.
20 Oct 2026
India–New Zealand FTA enters into force: zero duty on all Indian exports from day one
The India–New Zealand Free Trade Agreement came into force on 20 October 2026. From day one, New Zealand charges no customs duty on any Indian export, the first time India has got full duty-free access on all tariff lines at entry into force. New Zealand has also committed to facilitate USD 20 billion of investment into India, while dairy, sugar and edible oils stay protected.
20 Oct 2026